 Volodymyr Lukaniuk
Quick answer: A roof insurance supplement is a documented request to add items or quantities the insurer's first estimate missed: decking found rotten at tear-off, drip edge your village requires, a wrong square count. In Illinois your roofer may write that estimate and talk to the adjuster about the damage, but may not negotiate the claim for you.
A roof insurance supplement is the part of a storm claim most homeowners never hear about until the roofer says, "the insurance estimate is short, we need to send a supplement." The phrase sounds like a sales line. It describes an ordinary step: the first estimate was written before anyone could see the whole job, and the missing pieces are sent back to the same claim with proof.
We are a family-owned roofing company in Lincolnshire, working the north and northwest Chicago suburbs since 2018, and our team includes a claim analyst whose whole job is reading carrier estimates line by line. Below is what a supplement is, the moments it usually comes up, what Illinois law lets a roofer do with it, and what to keep in your own file.
What is a roof insurance supplement?
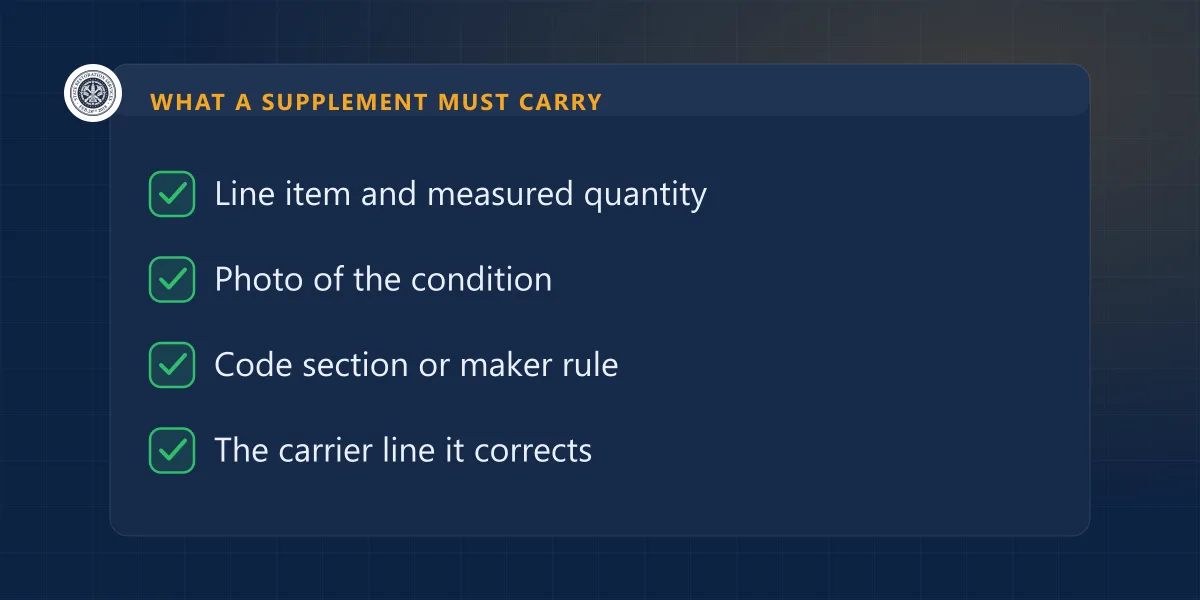
A supplement is a written request to the insurance company to add or correct line items on an approved roof claim. It carries the evidence for each item: a measurement, a photo, a code section or a manufacturer instruction. It does not reopen the question of whether the storm damaged the roof. It asks the company to price the job that the approved damage actually requires.
Most roof estimates in our area are written in Xactimate, the estimating software most large carriers use, and a supplement is usually written in the same format so the adjuster can compare it line by line. A supplement that only says "the price is too low" rarely gets anywhere. One that says "line 14 has 28 squares, the roof measures 31.4, here is the report" usually does.
When does a supplement come up on a roof claim?
Supplements come up at three points: when the first estimate is compared with a real measurement and the code, when the old roof is torn off and the deck is visible, and when the village inspector asks for something the estimate did not include. Each one has a different kind of proof, so it helps to know which one you are dealing with.
- Before work starts: the estimate is compared with the roof. An adjuster's estimate may be written from a short roof visit or from aerial imagery. When we measure, we compare squares, pitch per slope, eave and rake lengths, valleys and penetrations against the carrier's numbers. Our guide to how a roof is measured for an estimate explains where those numbers come from.
- During tear-off: damage nobody could see. Rotten or delaminated decking only shows once the shingles and underlayment are off. The crew photographs each bad sheet with something for scale, marks it, and counts the sheets before new decking goes down. That count and those photos are the supplement. We wrote separately about why decking is the one line nobody can price in advance.
- At inspection: the village asks for something. If the building department requires an item the estimate left out, the requirement itself becomes the evidence. Our article on code upgrades on a roof claim covers how ordinance-or-law coverage pays for it.
What may an Illinois roofer do with a supplement?
An Illinois roofer may write the estimate you send to your insurer, talk with the insurance company's representative about the damage, and discuss repair options. A roofer may not represent you on the claim, negotiate it, or file it for you. Those limits come from Section 18(i) of the Home Repair and Remodeling Act, and they apply to supplements the same way.
The statute lists what a contractor is still allowed to do, word for word:
"(1) providing an insured an estimate for repair, replacement, construction, or reconstruction of the insured's property and any such estimate may be submitted to the insured's insurance company; (2) conferring with an insurance company's representative about damage to an insured's property; or (3) discussing repair or replacement options with an insurance company's representative or the insured about options for the repair or replacement of the damage."
815 ILCS 513/18(i), Illinois General Assembly
The same subsection says a contractor "shall not call in or file a claim to an insurance carrier on the insured's behalf" and may not climb on a roof to inspect for exterior damage without the homeowner's express permission. Here is how that sorts out on an ordinary supplement:
| Step | Your roofer | You, or a licensed public adjuster |
|---|---|---|
| Measuring the roof and photographing hidden damage | Yes | — |
| Writing the supplemental estimate with quantities and code references | Yes | — |
| Sending that estimate to the insurer | Prepares it for you; you decide to submit it | Yes |
| Meeting the adjuster on the roof and pointing out damage | Yes, "conferring" about the damage | Yes |
| Arguing over price, coverage or settlement amount | No | Yes |
| Signing or agreeing to a settlement | No | You decide; a public adjuster can negotiate it |
When the conversation turns from "here is the damage" to "we disagree about the money," we hand it off. Our affiliated licensed public adjuster, State Adjusting Services, can represent you on the claim if you choose to hire them. Our storm and insurance page explains how the two companies keep those roles apart.
Which line items are most often missing from a first roof estimate?
The lines most often short on a first estimate are the ones a quick look cannot confirm: true square count and waste, drip edge and starter at the rakes, ice barrier at the eaves, steep and high-roof labor, flashing and pipe boots, and decking. Each one needs its own type of proof, listed in the table below.
| Line item | Why it gets missed | Proof that supports it |
|---|---|---|
| Square count and waste | Estimate built from imagery or a partial measurement | A measurement report or tape sketch with pitch per slope |
| Drip edge at eaves and rakes | Old roof had none, so nothing to "replace" | IRC R905.2.8.5, where the village has adopted it, and the permit |
| Starter strip at the rakes | Only eave starter is entered | The shingle maker's installation instructions; see our starter strip guide |
| Ice barrier at the eaves | Priced as ordinary felt | IRC R905.1.2 and the village's local requirement |
| Steep and high-roof labor | Pitch or story height not recorded | Pitch reading per slope and photos of the eave height |
| Step, chimney and wall flashing, pipe boots | Counted as "reuse" or left off | Close-up photos and a count of each penetration |
| Decking | Invisible until tear-off | Per-sheet photos and a sheet count made before covering |
None of these items is extra profit. Each one is material or labor the finished roof needs in order to pass inspection and keep the manufacturer's warranty. The steep and high-roof charges are the line we see argued about most, because pitch is hard to judge from the ground.
What happens after the supplement is sent?
The insurer reviews it and either approves it, approves part of it, sends an adjuster back to the roof, or denies it. Any change in the amount should arrive as a revised estimate. A denial should name the policy provision it relies on. Illinois claim rules give you the right to ask for both in writing.
Three Illinois rules matter here, and we cover them in more depth in the documents your insurer must send you:
- If your written estimate is higher than the company's, the company has to respond promptly in writing and either name a contractor who will do the work for its figure or account for the reasonable difference (50 Ill. Adm. Code 919.80(d)(7)(C)).
- If the claim is not settled within 75 days, the company has to tell you in writing why more time is needed (919.80(d)(7)(B)).
- A denial, in whole or in part, has to be in writing and name the specific policy language behind it (919.50(a)(1)).
If the company still says no, the path depends on what the dispute is about. A disagreement over quantity or price can go to a licensed public adjuster, and after that to the appraisal clause in your policy. A disagreement over whether the damage is covered is a coverage question, and appraisal usually does not settle that.
How does supplement money reach you?
On a replacement-cost policy, the first check is usually the actual cash value: the estimate minus depreciation and your deductible. Approved supplement items are added to the claim, and the withheld depreciation on the whole claim is usually released once the work is finished and the final invoice is sent.
Many policies built on the standard ISO homeowners form say the company will pay no more than actual cash value "until actual repair or replacement is complete," and they set a time limit for telling the company you intend to repair. Your own policy's Loss Settlement condition gives the exact wording and the number of days, so read it before the first check arrives. Our guide on recovering depreciation walks through the final-invoice step. If your mortgage lender is named on the check, this article explains how to get it released.
Your deductible stays the same when a supplement is approved. It is subtracted once per claim. A roofer who offers to "absorb" it through a padded supplement is asking you to sign off on an inflated estimate, and that exposes you as well as the roofer.
What to keep in your own claim file
- The carrier's first estimate and every revised estimate, with dates
- Your roofer's estimate and each supplement exactly as sent
- Tear-off photos of decking and flashing, with the sheet and penetration counts
- The permit, the inspection result, and any written note from the village
- Every letter or email from the insurer, especially any partial denial
Related reading: before a supplement there is the claim itself, so start with the Illinois storm claim from first call to final check; if the carrier's numbers are confusing, our notes on reading the line items of a roofing estimate help.
Frequently asked questions
What is a supplement on a roof insurance claim?
A supplement is a written request to the insurance company to add work or quantities that its first estimate left out, such as hidden decking damage found at tear-off, a code-required drip edge, or a corrected square count. It goes with measurements, photos and the rule that requires the item, and the company reviews it as part of the same claim.
Can my roofer send a supplement to my insurance company in Illinois?
A roofer may write an estimate that you can submit to your insurer, confer with the insurance company representative about the damage, and discuss repair options. Section 18(i) of the Illinois Home Repair and Remodeling Act lists those three things. The same section bars a contractor from representing you on the claim or filing the claim for you. Negotiating the claim on your behalf is the work of a licensed public adjuster.
How long does an insurance company take to answer a roof supplement?
There is no single deadline written for supplements. Illinois rules require the company to respond promptly in writing when you send a higher estimate, and to tell you in writing what is still being investigated if a claim is not settled within 75 days. In practice the answer depends on whether the company sends an adjuster back to the roof.
What if the insurance company denies the supplement?
Ask for the denial in writing with the policy provision it relies on. If the disagreement is about cost or quantity, a licensed public adjuster can take it up for you, and the appraisal clause in most homeowners policies is a further option. If the disagreement is about whether the damage is covered at all, that is a coverage question, and appraisal usually does not settle it.
Got an insurance estimate that looks short? Book a free inspection and we will measure the roof and compare it with the carrier's numbers, or call us at (866) 992-2982, Monday to Friday, 8:00 AM to 5:00 PM. We work across Lake and Cook County in the north and northwest suburbs.